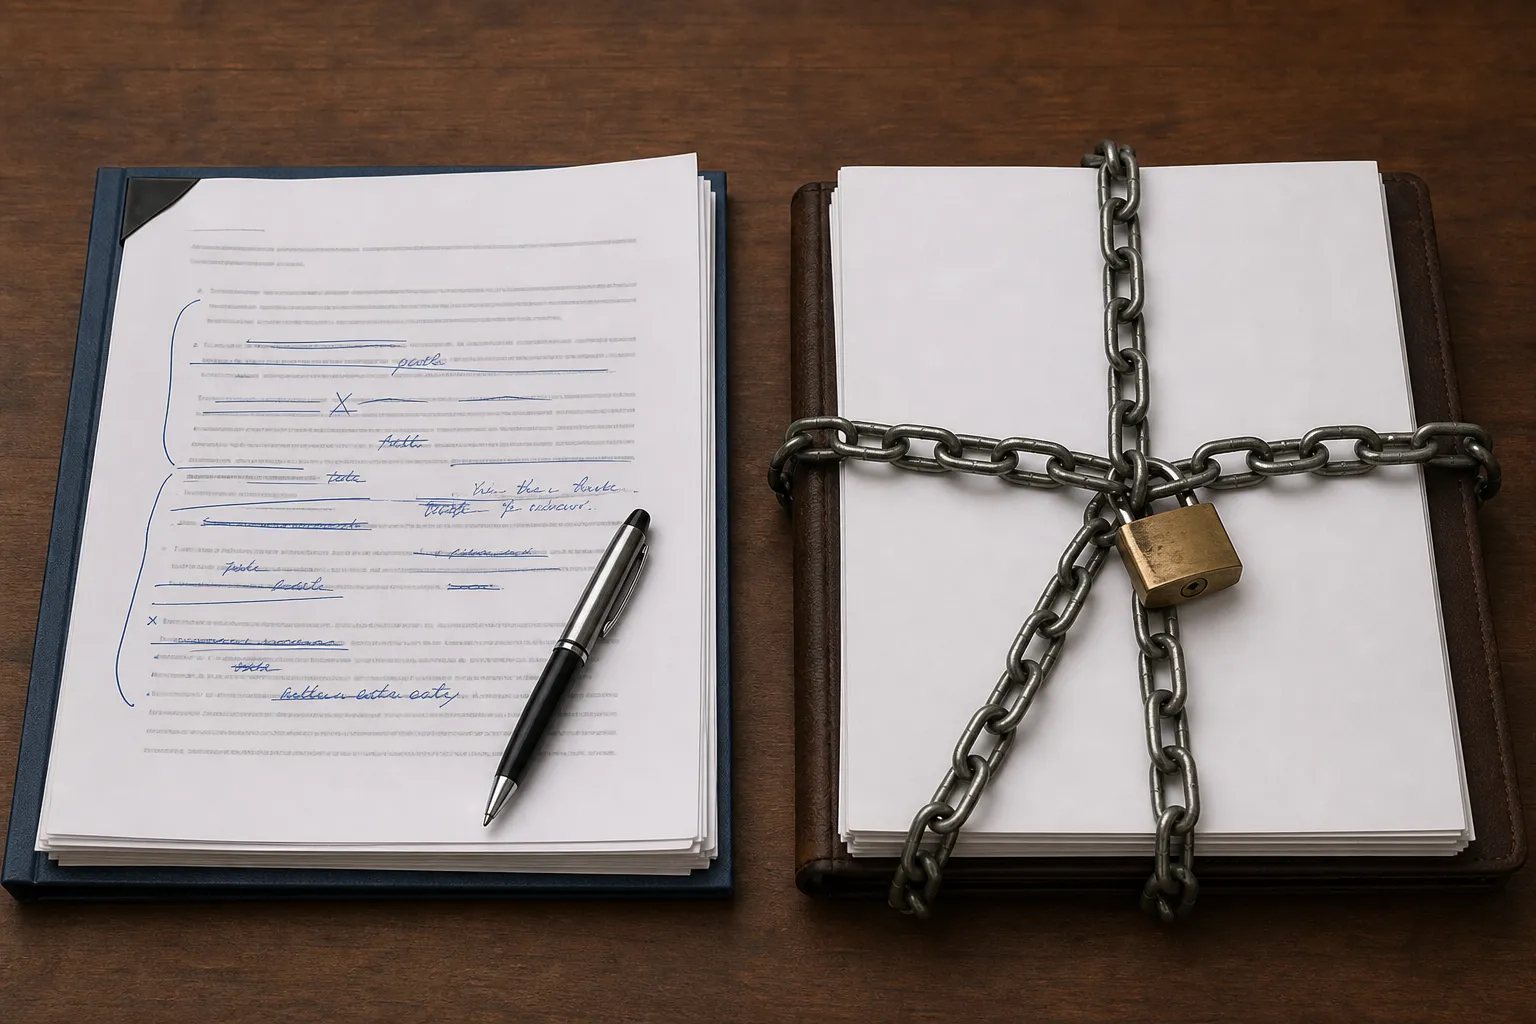
The short answer: a revocable trust can be changed while you’re alive, and an irrevocable trust generally cannot, and that one distinction drives nearly every other difference between them. For most people building an estate plan in California, a revocable living trust is the right foundation, while an irrevocable trust is a specialized tool layered on top when you need asset protection or estate-tax reduction. Below is how each one actually works, how they compare side by side, and how I help clients decide which fits.
Key takeaways
- A revocable trust can be amended or revoked during your lifetime and keeps your assets inside your taxable estate; an irrevocable trust generally cannot be changed, and it moves assets out of your estate.
- For most Californians, a revocable living trust is the correct foundation. An irrevocable trust is usually an addition, useful mainly when an estate is likely to exceed the federal estate tax exemption ($15 million per individual, $30 million per married couple in 2026, per Forbes Advisor).
- Assets moved into an irrevocable trust during your lifetime lose the step-up in cost basis at death, which for highly appreciated property can cost your heirs more in capital gains tax than the estate tax it saves.
- Probate avoidance is the weakest reason to pick a trust. The real value shows up in protections most plans skip: remarriage, divorce, elder financial abuse, and California-specific tax issues like Proposition 19.
What is a revocable trust and how does it work?
A revocable trust, also called a living trust, is a trust you can change, amend, or cancel at any time while you are alive and competent. You typically serve as your own trustee, so you keep full control of the assets: you can buy, sell, spend, and move property exactly as you did before. Nothing about your day-to-day financial life feels different.
For income tax purposes, a revocable trust is treated as a “grantor” trust, which means it is essentially invisible to the IRS and the state during your lifetime. You report the trust’s income on your own personal return, using your own tax rates. There is no separate trust tax filing to worry about while you’re living.
Two benefits matter most here. First, assets titled in the trust skip probate, so your family avoids the public, months-long court process. Second, because the trust is not a public record, your affairs stay private. The trade-off is that these assets remain part of your taxable estate, and they are not shielded from your own creditors or lawsuits, because the law still treats the property as yours.
One point people miss: because revocable trust assets stay in your estate, they receive a step-up in cost basis at your death. That reset can erase decades of capital gains for your heirs on appreciated real estate or stock, which is often worth far more than most families realize.
What is an irrevocable trust and how does it work?
An irrevocable trust is a trust that, once created and funded, generally cannot be changed or undone by you. You give up control of the assets and hand it to a separate trustee. There are narrow exceptions: some changes are possible if all beneficiaries agree, but that path can be slow and may require going before a judge, so you should plan as though the terms are locked.
Giving up control is the price you pay for two powerful benefits. First, once assets are transferred in, they are no longer part of your taxable estate, which can reduce or eliminate estate tax for very large estates. Second, because you no longer own the assets, they can be shielded from your creditors and from many lawsuits, which matters for people in high-liability professions.
There are real costs to weigh. An irrevocable trust is its own taxpayer, and trust income is taxed on a compressed schedule: in 2026, a trust reaches the top 37% federal rate once its income passes just $16,000, far sooner than an individual would. Assets moved in during your lifetime also lose the step-up in basis at death. For highly appreciated property, that lost step-up can hand your heirs a larger capital gains bill than the estate tax you were trying to avoid.
Revocable vs irrevocable trust: how do they compare?
Here is the practical side-by-side that I walk clients through.
| Feature | Revocable trust | Irrevocable trust |
|---|---|---|
| Can you change it? | Yes, anytime while competent | Generally no; exceptions need beneficiary consent or a court |
| Who controls the assets? | You (usually your own trustee) | A separate trustee |
| In your taxable estate? | Yes | No, once funded during life |
| Creditor / lawsuit protection | Little to none for your own debts | Strong, once assets are transferred |
| Step-up in cost basis at death | Yes | No, for assets moved in during life |
| Income tax treatment | Reported on your personal return | Separate return, compressed brackets |
| Avoids probate | Yes | Yes |
| Kept private | Yes | Yes |
| Best suited for | Core estate planning for most people | Large estates and specialized asset protection |
Which trust should you use, and who actually needs an irrevocable one?
For most people, a revocable living trust is the right choice for core estate planning, and an irrevocable trust is a specialized addition, not the starting point. As Forbes Advisor puts it, everyone needs a basic estate plan, but not everyone needs an irrevocable trust. I use a few clear criteria to sort this out.
You are likely well served by a revocable trust alone if your estate is comfortably below the federal estate tax exemption, you want to keep full control of your assets, and your main goals are avoiding probate, maintaining privacy, and preserving that step-up in basis for your heirs. That describes the majority of the families I work with, including many retirees and business owners in their 50s to 70s.
You may benefit from adding an irrevocable trust when one or more of these applies:
- Your estate is likely to exceed the federal exemption, so estate tax reduction becomes a real dollar issue.
- You work in a profession with meaningful lawsuit exposure and need assets legally separated from your name.
- You want to plan around long-term care or specific creditor risks for a beneficiary.
The decision is rarely all-or-nothing. A common structure is a revocable trust as the foundation, with a targeted irrevocable trust holding specific assets that need protection or estate-tax treatment. If your estate is large or complex, this is where advanced estate and tax planning earns its keep, because the wrong asset in the wrong trust can quietly cost your family six figures in avoidable capital gains.
Why probate avoidance is the wrong reason to choose a trust
Most estate planning conversations start and stop at probate avoidance, and I think that focus is backwards. A trust that only dodges probate is what I call a “will substitute”: it moves assets around a court process and does nothing else. In California, a properly built revocable trust can do far more, and the deeper protections are where the real value sits.
Six protections get overlooked in the rush to avoid probate:
Remarriage protection. Without it, assets meant for your children can end up with your surviving spouse’s new spouse or their family. A well-structured trust can care for your spouse and still guarantee that what remains passes to your children.
Divorce protection for your children. In California, an inheritance starts as separate property, but it can quietly become community property if it gets commingled, and then it is exposed in a child’s divorce. A trust can keep that inheritance walled off. I cover the mechanics in protecting your kids’ inheritance from divorce.
Financial elder abuse protection. Elder financial exploitation is a growing concern in California. Safeguards in the trust can guard against undue influence, including a situation I see too often, where one child pressures a parent to cut out the others.
Asset protection for heirs. Even responsible heirs can face lawsuits, creditors, and unexpected liabilities. Structuring how they receive their inheritance can shield it after you are gone.
Protecting beneficiaries from themselves. Many inheritances are spent within a few years. Staggering distributions by age, milestone, or achievement (education, a first business) can prevent rapid depletion and encourage the values you want to pass on.
Tax planning beyond estate tax. California’s tax landscape is complex, and Proposition 19 has made property tax reassessment a live issue for families passing down real estate. Careful planning can address capital gains, income taxes, and property taxes, and in some cases defer income taxes on retirement accounts for years. A good plan minimizes taxes; a great plan also maximizes real estate depreciation for your beneficiaries going forward.
If you want a wider view of what trips families up, our list of common legacy missteps is a useful gut check. The guiding principle I give every client is simple: start early, and review the plan regularly, because life events and law changes can outdate even a well-built trust.
Frequently asked questions
Can you change an irrevocable trust after it’s created?
Usually not on your own. An irrevocable trust is designed to be permanent, so you generally cannot amend or revoke it once it is funded. Some changes are possible if all the beneficiaries agree, but the process can be lengthy and may require court approval before a judge. Plan as though the terms are locked in.
Does a revocable trust protect my assets from creditors or a lawsuit?
No, not from your own creditors. Because you keep control of the assets in a revocable trust, the law still treats the property as yours, so it remains exposed to your creditors and to lawsuits against you. If shielding assets is a real concern, an irrevocable trust is the tool that provides that protection, since you no longer own the transferred assets.
Do you save on taxes with an irrevocable trust?
Sometimes, but not always, and the answer depends on your estate size and asset mix. An irrevocable trust removes assets from your taxable estate, which can reduce estate tax for estates above the federal exemption. The trade-off is that those assets lose the step-up in cost basis at death and the trust pays income tax on a compressed schedule, reaching the top 37% federal rate at just $16,000 of income in 2026. For many families, the lost step-up costs heirs more than the estate tax it saves.
Which trust avoids probate in California?
Both a revocable trust and an irrevocable trust avoid probate in California, as long as your assets are properly titled in the trust’s name. Probate avoidance alone should not decide which one you use. A revocable living trust handles probate avoidance for most people, while an irrevocable trust is added when you also need asset protection or estate-tax reduction.
Do I need both a revocable and an irrevocable trust?
Many people do not, but some do. A revocable living trust is the foundation for most estate plans and handles probate, privacy, and the core protections. An irrevocable trust is layered on when your estate exceeds the federal exemption or you need serious asset protection, often holding only specific assets while the revocable trust holds the rest.
The right structure depends on your estate size, your family situation, and your goals in California specifically. WE Alliance Wealth Advisors has helped families plan legacies as a fiduciary RIA in Roseville since 1992. If you want a plain-language read on which trust fits your situation, call us at 916-325-0130 or request a comprehensive financial planning review, and our team will reach out the next business day.
WE Alliance Wealth Advisors
Latest posts by WE Alliance Wealth Advisors (see all)
- Revocable vs Irrevocable Trust: Which Fits Your Estate - October 2, 2026

 3001 Douglas Blvd, Suite 142
Roseville,
CA 95661